You’re off work as a result of illness or injury. On a better day, you meet a friend for coffee and smile for a photo.

Now imagine your insurance company pointing to that same image as a reason to question your long-term disability (LTD) benefits.
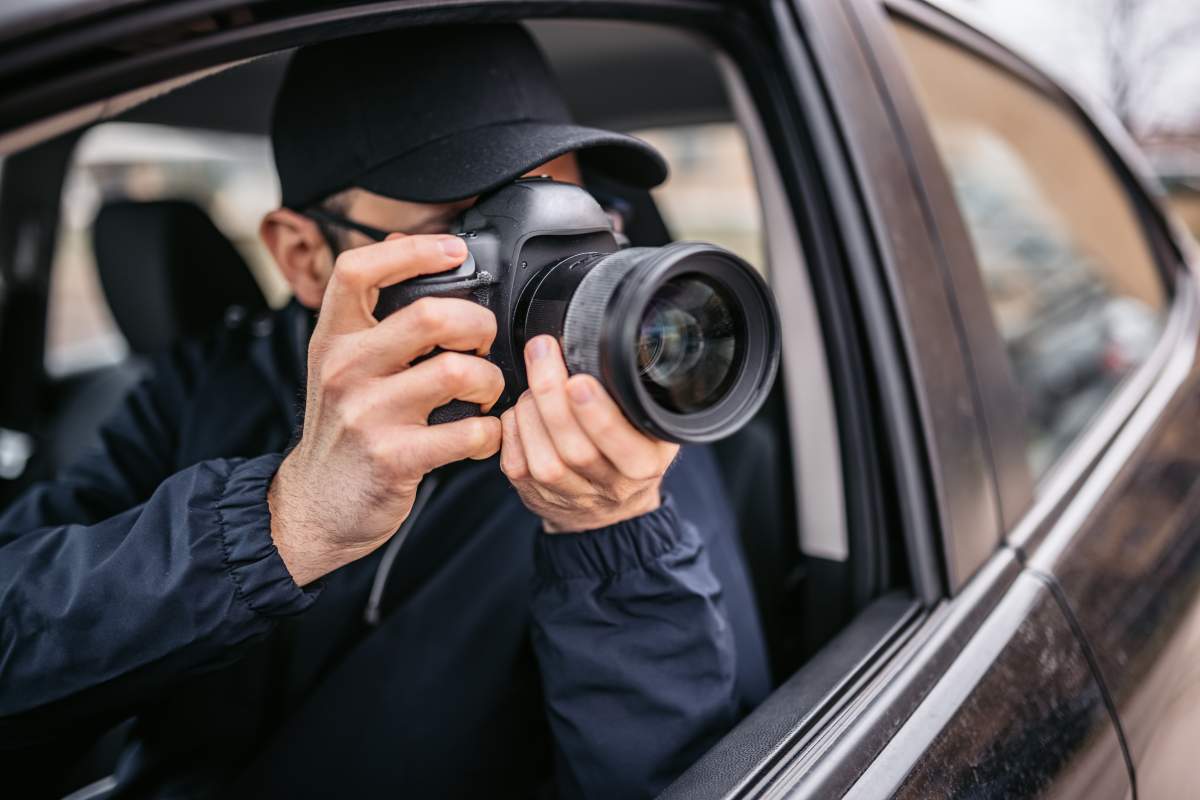
Insurers may scrape your public social media posts or hire investigators to observe your activities. They still have to follow privacy rules.
For someone relying on those payments to cover the mortgage or groceries, that can be frightening. But a photo doesn’t automatically prove you’re ready to return to work.
READ MORE: Invisible illnesses: Can I still get long-term disability even if I don’t look sick?

- A good day doesn’t mean you’re ready to work
Get breaking National news
A short surveillance clip of you carrying a grocery bag may not capture that you needed help getting through the store or the pain you felt afterwards.
A smiling photo doesn’t show whether you can concentrate, manage symptoms or reliably get through a workday.
Your eligibility for LTD depends on your policy and how your condition affects your ability to work. You can still qualify while being able to do some everyday activities.
My advice is to be accurate about your limitations. If you can walk for 10 minutes before needing a break, explain that. Give your doctor and insurance company a clear picture of both your better days and your difficult ones.
- Julie Austin’s case shows why context matters
Our firm represented Julie Austin, a Barrie teacher who suffered a brain injury after being assaulted by a student. Global News covered her fight for disability benefits.
Her insurer relied on surveillance photographs to question her claim. My colleague James K. Fireman showed that the photos actually supported her disability. Our firm helped Julie recover $113,000 in compensation and fought for additional benefits.
Julie’s case shows why surveillance needs to be considered alongside the medical evidence and the demands of working.
READ MORE: Denied long-term disability? 4 reasons to get your insurer’s decision in writing
- Get help if your insurer cuts you off
If your insurer denies or cuts off your benefits, ask for its reasons in writing. If it points to surveillance, ask for the photos, video and reports it’s relying on. A disability lawyer can help obtain and assess that information.
Take the insurer’s letter and any photos or footage you receive to your doctor. Ask them to explain how your condition limits your ability to work and whether the material changes their opinion. If it doesn’t, their report should explain why.
Spell out how long the activity lasted, whether you needed help and whether you had to rest afterwards. Those details can help your doctor and lawyer understand what the camera didn’t capture.
Before starting an appeal or sending a detailed response, speak with a disability lawyer. Get advice promptly so you understand your options and any deadlines.
READ MORE: Insurer being difficult? 3 reasons you should hire a long-term disability lawyer